• Skip to main content
  • Skip to secondary menu
  • Skip to primary sidebar
  • Skip to footer
  • Home
  • About Us
  • Say hello
Rethink Real Estate. For Good.

Rethink Real Estate. For Good.

  • Podcast
  • Posts
  • In the news
  • Speaking and media
    • About Eve
    • Speaking requests
    • Speaking engagements
    • Press kit
  • Investment opportunities

Investing

Know your price.

May 12, 2021

Andre Perry is a senior fellow with the Metropolitan Policy Program at Brookings and a scholar-in-residence at American University. He writes for The Hechinger Report, and has been published by The Nation, The New York Times and The Washington Post. Last year, Andre put out a new book based on his work: Know Your Price: Valuing Black Lives and Property in America’s Black Cities, which explores urban development in cities across the country, and how it has so often failed Black communities.

This story is also a personal one. Andre talks about growing up in the Pittsburgh region, in the township of Wilkinsburg. He has described how he has watched over the years as this community remains stagnated, and without meaningful investment, while neighboring areas experience remarkable economic revivals.

Andre began his career focused on education, but his work has expanded to examine the myriad ways government policies have ‘created housing, education, and wealth disparities’ that continue to disadvantageously impact minority communities in urban metro areas. Andre has written on subjects as diverse as infrastructure, how our children are driving climate action, student debt cancellation, access to fertility treatments, and supporting Black businesses. He also served as the Founding Dean at the College of Urban Education, at Davenport University in Grand Rapids, an institution he helped to plan and launch.

Insights and Inspirations

  • Institutionalized racism creates an ‘unconscious bias,’ where we are willing to blame the people who have been marginalized rather than the policies that made it possible. And so, we recycle discrimination over and over and over. If we don’t see the problem, we have no incentive to change it.
  • Andre found that in neighborhoods where the share of Black population was 50 percent or higher, homes were underpriced by 23 percent, or $48,000 per home … $156 billion in lost equity.
  • These communities should have access to the same information, data, research, and ideas as corporations, cities and state governments … so they can come to the table empowered.
  • We need to create a culture of inclusion where all people are valued, and to do this we need innovations. We need new mortgage products. We need new appraising systems. We need new tax assessment systems.
Read the podcast transcript here

Eve Picker: [00:00:10] Hi there, thanks for joining me on Rethink Real Estate. I’m on a mission to make real estate work for everyone. Real estate can help to solve climate change, can house people affordably, can create beautiful streetscapes, unify neighborhoods and enliven cities. So I’m on a journey to find the most creative thinkers and doers out there. I’m not the only one who wants to rethink real estate. You can learn more about me at EvePicker.com or you can find me at SmallChange.co, a real estate crowdfunding platform with impact real estate investment opportunities open for investment right now. And if you want to support this podcast, please join me at Patreon.com/rethinkrealestate, where there are special opportunities for my friends and followers. Today, I’m talking with Andre Perry, a senior fellow at Brookings in Washington, D.C. Andre is also a scholar in residence at American University, a columnist for The Hechinger Report, and he writes for the Nation. But what really drives Andre is the seemingless impossible divide between blacks and whites in this country. He is focused in his recent work on the multiple issues impacting minority communities in urban metro areas. And he has authored a book, published in 2020, called Know Your Price, Valuing Black Lives and Property in America’s Black Cities. In his work at gathering data for the book in black majority cities across the country, Andre found that homes in black neighborhoods where the share of population was 50 percent or higher were valued at about half as much as white neighborhoods. Andre further refined the data by taking into account education, crime, walkability and other key neighborhood factors. And still, he found that homes in black majority neighborhoods were underpriced by 23 percent, or about 48,000 dollars per home. That’s 156 billion in lost equity. And Andre knows we have to fix that. If you’d like to join me in my quest to rethink real estate, there are two simple things you can do. Share this podcast or go to Patreon.com/rethinkrealestate to learn about special opportunities for my friends and followers and subscribe if you can.

Eve: [00:03:18] Hello, Andre, and I’m just really delighted to have this opportunity to talk to you.

Andre Perry: [00:03:22] Well, thanks for having me. I’m looking forward to the conversation.

Eve: [00:03:26] Great. There’s lots to talk about. You’ve thought and written about multiple issues impacting minority communities and urban metro areas and most recently in your book, Know Your Price, Value in Black Lives and Property in America’s Black Cities. So, first of all, I wanted to ask you, because I’ve also read other things that you’ve written, and I’d like to know what you mean by the term unconscious bias.

Andre: [00:03:54] Well, unconscious bias is when you act without thinking. It’s essentially the responding to a narrative that we generally know and accept. It’s like when people say the American dream, we all have an idea about what that means, and we respond to it. But when it comes to Black Americans, we also have an idea in our head that if anything goes wrong, we blame Black people. And so without thinking, without batting an eye, if there are problems in Black neighborhoods, we say, oh, it must be the character of the residents. It must be crime. It must be something else. We never look at policy implications or we don’t look at policy makers behavior. So for me, when I talk about unconscious bias, I generally refer to how we assume that Black people are the problem when considering the issues in Black neighborhoods and cities.

Eve: [00:05:09] Right. So what’s been the overall impact of this unconscious bias and what’s the impact today? I mean,

Andre: [00:05:17] You know, we talk a lot about unconscious bias, but at its heart is really just plain discrimination.

Eve: [00:05:24] Emotion, yeah.

Andre: [00:05:24] Like that. You know, it’s when you talk about, for instance, redlining. It was the practice of the federally backed Homeowners Loan Corporation in the 30s and throughout to the 70s, the practice of saying that Black neighborhoods were too hazardous or or they weren’t worthy of low interest loans to help develop those those areas. But it was predicated on this, the effort to isolate Black people in communities.

Eve: [00:06:00] Wasn’t that conscious bias rather than unconscious bias?

Andre: [00:06:03] Yeah, I mean, but it was also just fueled by this belief that Black people and white people should not live together. And there was a conscious effort to bring that belief into policy. And so, you know, I you know, I talk a little bit about conscious bias in my work, but the source of a lot of our implicit or tacit assumptions are racist policy. Conscious, conscious, racist policy. And so we can’t let policy off the hook for our behaviors. I tend to blame policy, not people. I just I find it more useful to get at the root for me. And that’s policy. And that, for me, represents that conscious effort to suppress Black people based on a hierarchy of human values.

Eve: [00:07:08] Right. Yeah, that’s, I think, very conscious and really disturbing. But, you know, I have to wonder about all the unconscious bias out there that just perpetuates things a little longer, makes it a little harder to get where we need to go.

Andre: [00:07:23] You know, a lot of my work, I look at home values. What anchors the book Know Your Price is a housing study we did a few years back where we looked at the average price of homes in areas where the share of the Black population is 50 percent or higher and compared them to areas where the share of the Black population is less than a percent. And we controlled for education, crime, walkability, all those fancy Zillow metrics. And what we found is that homes in Black neighborhoods are underpriced by 23 percent, about 48,000 per home. Cumulatively, that’s 156 billion in lost equity. That’s the money people use to lift themselves up by their proverbial bootstraps. It’s the money municipalities use to fund everything from education to infrastructure to policing. But, you know, there’s a way to interpret that 23 percent difference. Again, we controlled for education, we controlled for crime. And certainly, crime and education mattered. They lower price, but that there’s still a gap. And it’s almost as if people, when they see Black neighborhoods, they see twice as much crime than there actually is. They see worse education than there actually is. So there is a perceptual issue here. That when evaluating or assessing taxes, when appraising homes or any kind of subjective task is at hand, people lean on these tropes of Black neighborhoods. And and so there is something psychological in nature that’s reducing the value in Black neighborhoods in ways that it shouldn’t. So there is something there when you’re talking about unconscious bias.

Eve: [00:09:36] So as you mentioned, this bias spills over into investment and who has wealth and who does not. And, you know, as a real estate developer, I’ve certainly seen how it works with appraisals because, you know, banks will lend based on appraisals and appraisals in existing neighborhoods have a certain value. And if they’re already devalued, what’s going to disrupt that and raise the value? You know, it’s just a huge dilemma.

Andre: [00:10:06] Yeah. You know, the price comparison model is an example of structural racism. I mean, a good example of structural racism. So, as you mentioned, when an appraiser has to find a comparable home and they stay in the neighborhood, that’s already been discriminated against, you’re essentially just recycling discrimination over and over and over.

Eve: [00:10:27] Exactly. So how do you disrupt that?

Andre: [00:10:30] Oh, so one, you can you don’t necessarily have to stay in the neighborhood for finding comparables. I mean, what’s interesting is like for our data, we looked at the entire metro area and compared homes with similar social circumstances. So you can find, using big data, you can find homes in areas that have similar educational levels, similar crime levels, all those different things. And you don’t necessarily have to compare it to another home in the same neighborhood.

Eve: [00:11:07] Yeah, but then you’re dealing with an industry that’s used to doing that. So really, the disruption has to come with the entire banking and appraisal industry. How do you make them look elsewhere? Like what prompts? You know, I was one of the first loft builders in Pittsburgh and I went through this myself because there were no comparables. And so I talked to appraisers about like, well, you know, look at that project. It’s not in the same neighborhood, but it’s offering a similar product. And they did. You know, they had to because it was the beginning of something new and there wasn’t anything else to look at. But when you have, you know, five other houses that have sold in a neighborhood, like Wilkinsburg, where I know you grew up or Garfield and that’s the easiest go-to, how do you disrupt that behavior?

Andre: [00:11:57] Yeah, but I think you said a word that is really relevant to the conversation. You make them.

Eve: [00:12:05] Ahhhh.

Andre: [00:12:06] You know, one thing I learned about this protest movement over the last few years, but really culminating in the summer of 2020 is that people do have power. This is a power issue. And the same way we created a culture of exclusion, we can create a culture of inclusion where people are valued, all people are valued. And we need innovations, no question. We need new mortgage products. We need new appraising systems. We need new tax assessment systems, and we should open ourselves up to that. But clearly, people in various industries aren’t going to do that themselves. They’re going to have to be backed into it. So I encourage communities to mobilize, organize and fight back. The typical thing that has incited structural change in the United States, it’s litigation.

Eve: [00:13:14] Right, right.

Andre: [00:13:14] So that is a tool. But I also just think that we are going to have to pressure banks and appraisal, the various industries in housing to take new approaches. Because those approaches are the tools that reify discrimination in this country, and it goes beyond appraisals and lending. You’re talking about zoning structures as well.

Eve: [00:13:47] Yes. Yes.

Andre: [00:13:47] You know, you’re talking about building.

Eve: [00:13:50] My backyard. Yeah.

Andre: [00:13:52] Yeah, exactly. And so there’s all these structures that maintain exclusion and bias. And we need to demand change in all of those structures. So and that’s where, you know, for my book, Know Your Price, there’s a theme, there’s you know, I want people to demand their proper value. And it’s not going to come because someone else says this is what it should be worth or, it’s going to come by people from places like Wilkinsburg, Homewood, Garfield, demanding their proper value.

Eve: [00:14:37] Right.

Andre: [00:14:37] And so for me, it’s, you said the word make. Yeah, that’s what it’s going to take.

Eve: [00:14:43] Yeah, I think you’re probably right. So the interesting thing is also, you know, there are developers who, developer it isn’t always a bad word, who really want to work in these neighborhoods. And they can’t because of this entire sort of pricing structure becomes impossible. It doesn’t matter if you build a house in Wilkinsburg or Garfield or downtown, the construction costs are going to be the same. Right?

Andre: [00:15:09] Yeah.

Eve: [00:15:09] But the market’s really different. So that is a huge problem. But also, I’ve always been really sort of irritated and puzzled by the affordable housing market, which almost demands a product that looks the same. So, I think when you talk about value, you know, good design, different design, innovative products can bring a different value as well. And I don’t think people think about that very much. You can drive down a street in Pittsburgh and, you know when you’re on a street which has affordable housing because it all looks the same.

Andre: [00:15:44] Yeah.

Eve: [00:15:46] It’s bad branding, right?

Andre: [00:15:47] Exactly. And I’m not a real estate person in the sense I’m not a practitioner. I’m a researcher. But I’ve been saying, hey, there needs to be innovation in the actual end products that we put up. You know, we’ve got to show how diverse products can look and serve diverse communities. We’ve got to have innovation in lending and in ownership. Like we need new cooperative models. We need new everything from credit scoring systems to zoning ordinances. But I will say this, that at some point you need more capital directed in the right way.

Eve: [00:16:37] Yes.

Andre: [00:16:38] And so for me, it’s also about understanding the role the federal government has to play in creating inclusive communities. Because remember, it was the federal government largely that created the problem we’re in today. They, instead of distributing resources equitably in the 30s, 40s, 50s, 60s, they distributed resources to help communities, to build up communities and wealth, really among white residents and not Black. So, the same approach as we used in the 30s, 40s, 50s to help people build up communities, we can use today. But when it comes to Black people, we don’t want to give Black residents low interest loans and grants and down payment assistance. And and we don’t want to reward developers for actually creating inclusive homes and facilities. We then hide behind the sort of, you can’t create any kind of race based program that’s reverse discrimination. But the reality is, if you really create some type of equitable strategy, you almost have to target your investments towards people who have been disenfranchised or injured by past policy.

Eve: [00:18:09] Right.

Andre: [00:18:10] And it happens to be Black people and we should not shy away from that. And then it happens to be in places that you have significant Black populations, not completely all Black people in Wilkinsburg or Homewood or Garfield, but those are the places we need to find a way to direct capital to and in ways that just makes sense.

Eve: [00:18:33] Yes, yes.

Andre: [00:18:34] And there’s this reticence to drive capital based on need. And until we solve for that, it’s going to be hard to really do what we need to do.

Eve: [00:18:48] So you’ve also talked about the devaluation of Black owned homes, and I want to hear a little bit more about that. How how did you calculate that?

Andre: [00:18:57] At the core, you know, I’m from Wilkinsburg and I come back home all the time,

Eve: [00:19:02] We should explain to people who are listening to this, because we have listeners all over the country, maybe even the world. So, Wilkinsburg is actually a beautiful neighborhood town on the outskirts of Pittsburgh that has amazing architectural building stock and has just sort of stagnated and leaned in really poor condition for a very long time, presumably because it is predominantly a Black demographic. Is that a good explanation?

Andre: [00:19:34] Yeah. And it’s you know, growing up in Wilkinsburg, I really didn’t know the difference between Wilkinsburg and Pittsburgh, because Wilkinsburg is a Black majority municipality borough surrounded by Pittsburgh on three sides.

Eve: [00:19:49] Oh, I didn’t know that actually. Yeah.

Andre: [00:19:51] Yeah. And the people generally were the same. I mean, in the parts of Pittsburgh that it was adjacent to was Black. Wilkinsburg was majority Black. It had thriving commercial corridor, and it had all the quote unquote assets that you would look for when considering to develop a place. It’s close to downtown, close to the university. It has its own highway. It had parks. It has everything.

Eve: [00:20:22] There’s even a busway stop there.

Andre: [00:20:24] Busway. I mean, there’s…

Eve: [00:20:26] Like ten minutes to downtown. It’s amazing.

Andre: [00:20:28] I mean, it has literally everything you would want. But when U.S. Steel left town or downsized considerably, white residents moved, leaving a majority Black population and investment just stopped. And in any situation, I mean other situations, if you said if that area had majority white people in it, there would be no question there will be development there, because, as you mentioned, housing stock was excellent. You had a thriving commercial corridor.

Eve: [00:21:07] Yeah, the main street’s lovely.

Andre: [00:21:09] Exactly. You had everything there. And so, when I go back home, it is like stupefying to look at why isn’t investment coming? And right next door in Pittsburgh, which similar situation in terms of access to transportation, great housing, universities nearby, commercial corridor. But there was a decision to bring Google into town. And Google could have landed in Wilkinsburg. They chose Pittsburgh. And I talk a lot about bias in bias out. And so, in the planning for Google to come to Pittsburgh. To site itself in a former Nabisco factory where Black people used to live around. All the planning was essentially with white people. And if you look at that part of Pittsburgh now, it’s thriving, it’s booming. It has restaurants, shops,

Eve: [00:22:18] It’s actually gentrified, which is a little shocking.

Andre: [00:22:21] But you don’t see Black people.

Eve: [00:22:23] No, I know that. You know, I did a couple of developments in East Liberty before Google came along. And the last thing in the world I wanted to see was that neighborhood gentrify.

Andre: [00:22:36] Yeah.

Eve: [00:22:37] And I was absolutely shocked to see it happen over the period of probably 18 months. It went from Black people on the street to what looked like people visiting from the suburbs. I don’t know how else to say it, but it was it was actually shocking to watch. It was like for one moment in time, it was a great mixed, diverse neighborhood and then it was over. How can you, like, stop it right there, you know, when it’s at the great, mixed, diverse neighborhood point?

Andre: [00:23:06] But that’s why we need more housing policy connected to our economic development policy.

Eve: [00:23:15] Yep.

Andre: [00:23:16] And oftentimes they’re running on parallel tracks, never to touch. And it, my belief that some of that is intentional. That there are many people who don’t want to see Black people around a new development. And so, when you plan with all or mostly all white people with the muckety mucks of places like Pittsburgh and not include others in your development, you get what you get. And so I always say that. The developments really reflect who’s involved. Now, and it’s difficult because when you’re talking about planners and architects and economic development folks, largely white crowds and so…

Eve: [00:24:08] Also, largely white male crowd.

Andre: [00:24:11] Yes, that’s right.

Eve: [00:24:12] I want to point that out because I’ve been the only female in the room for a long time.

Andre: [00:24:16] Exactly. Very. A lot of testosterone in the room.

Eve: [00:24:21] Yes.

Andre: [00:24:22] Right. Lots of it. And so, and then people look up when the project started to go, why does it look pale and male? Because the planners were pale and male, you know? So you have to be very intentional about making sure people are included in any kind of development. And so, whether you are in Pittsburgh or Philly or Birmingham or Detroit or Baltimore, you just have to be very deliberate about including people. And we have to make every effort to concretize inclusion into policy. You know, I wrote something not that long ago that talked about, on the federal government side, that we need equity scoring system. This, just the way we score legislation against its potential impacts on the budget. We should score policies and practices on its potential impact on Black and brown communities. And so, when you’re developing a project, you’ve got to demonstrate how is this going to boost employment? How it’s going to boost ownership? How are Black people going to share in the prosperity? If you don’t see a clear path, then we should not greenlight these projects.

Eve: [00:25:42] Yeah.

Andre: [00:25:43] Not only must we build a culture that supports inclusion. That culture must build policy to protect for inclusion.

Eve: [00:25:56] Right. So, in your book, you also talk about wanting to give Black communities and home-owners information to stand on to empower them. But how do you do that? I’ve been involved in community meetings in neighborhoods like Garfield and it’s excruciatingly difficult. Do you want to explain what you’re doing? You are faced with a crowd of people, some of whom are just trying to get by. And as a small developer, it’s just it’s you want to do the right thing. It’s just really hard to know how to do it.

Andre: [00:26:32] Yeah, but this is why we need to really work with community members. It’s a lot easier when you’re of the community. When people recognize you as a member of a particular community. So when I come back to Wilkinsburg, although I’ve been fairly distant for most of my professional career, when I go back, people go, oh, Andre, he’s down with us. He believes in us.

Eve: [00:26:56] They trust you.

Andre: [00:26:57] They trust me.

Eve: [00:26:58] Right.

Andre: [00:26:59] And so when I talk with developers, I see, you know, a lot of this work and it’s hard work. But you got to think of yourself as becoming a member of a community first, because when you’re a member of a community, it’s so much easier to communicate. It’s so much easier to share the benefits and the trade-offs. And it’s so much easier to be honest. And so one of the reasons why I wrote Know Your Price, it’s a policy book, but it’s there’s a lot of stories in there, personal narrative, biographies. Because one of the goals of the book was to introduce this idea of devaluation, not making it a policy wonky type of thing, but really explain it through the lived experience. And when you run through the lived experience, keep, it resonates with community members. So that was my goal of the book. But it’s something that everyone should take on. They should see themselves as becoming a member of a community because communication becomes so much easier.

Eve: [00:28:20] Interesting. So, I also want to shift to your partnership with Ashoka. The Brookings Ashoka Partnership, and explain what you’re trying to accomplish there. And also, what Ashoka, I know a little bit about Ashoka, but not a lot. So it would be great to hear something about this.

Andre: [00:28:38] Ashoka is a social entrepreneurship organization that really tries to incubate or incentivize systems changing ideas. So, if you have an idea that will change some system, they fund or incentivize through these through fellowships or competitions to find interesting and innovative approaches to solving problems. So, when I presented this issue of housing devaluation, someone from the Ashoka organization reached out and said, hey, this is the kind of problem that requires a systems changing idea. So, after a year worth of planning and discussion, we landed on a competition, a challenge, competition of sorts. Collaborative competition, I should say. That we’re looking for innovations that will find those systems changing ideas that will solve for housing devaluation. So, if you are out there and we’re going to have a million dollars’ worth of prize money that we’re going to use as incentive. So we’ll be giving away different prizes totaling a million dollars to people who may have new zoning ordinances they want to put forth. New credit scoring systems. New cooperative ownership models. If you have a solution, we want to hear about it. All you have to do is Google Ashoka Brookings Collaborative Challenge and you’ll get all the information. But it was my way of really saying, hey, how can we incentivize people who are proximate to the problem to solve for this issue? And so we launched it a few months ago, but people can start enrolling in the competition in the summer. Right now, we’re just simply mapping ideas, looking for different approaches and so we can then categorize them. But people will be able to join in this collaborative challenge starting this summer.

Eve: [00:31:09] That sounds really fabulous.

Andre: [00:31:11] Yeah, it’s fab because, you know, when you work in a think tank, I’m a senior fellow at Brookings. We’re good with identifying problems, sometimes not as good as identifying solutions. So, this is really my effort to say, hey, here are some solutions that will be community driven. Not coming from up high, from somebody in D.C. These are solutions driven by community members. And so that’s the whole point.

Eve: [00:31:46] So if you could imagine the country 10 years from now, how would you like to see it changed?

Andre: [00:31:53] I want to see a country in which there’s a culture that supports reparative strategies. You know that I want to see these kind of policy changes come from a change in culture. For so long we’ve created a culture of exclusion and that led to everything from redlining to exclusionary zoning to employment discrimination. All these things are supported by an exclusive culture. I want to see 10 years from now a culture that supports reparations, inclusionary zoning, other policies that repair the damage that was caused by discrimination. And that’s going to take people who are talking about repair, talking about inclusion, talking about the value of diversity, and if we do this enough, we can shift the culture. And so that’s what I want to see.

Eve: [00:33:07] I’ve thought about this a lot. And I think for me, it’s I’d love to see a culture of trust. And that would probably only be built after everything you’ve said. But the mistrust is really, I think, stopping us moving forward really big time. And so, I’d love to live in this country and not feel like I’m mistrusted because I’m white or not feel like I might mistrust someone because they’re Black. That would be a really lovely thing. Don’t you think?

Andre: [00:33:40] Oh yeah. I mean, you know, that’s certainly core.

Eve: [00:33:44] Yes.

Andre: [00:33:44] We really don’t trust each other.

Eve: [00:33:47] No, I think that’s …

Andre: [00:33:47] As you know, developing trust is a process.

Eve: [00:33:51] It certainly is.

Andre: [00:33:52] I think if we are willing to put ourselves in that process, then we can gain trust. It is achievable to be a trusting, loving reparative culture.

Eve: [00:34:07] So what’s next for you? Final question.

Andre: [00:34:10] Oh, man, I’m I have this Ashoka Brookings Collaborative Challenge. I have reports coming up. But, you know, I’m going to continue to fight for justice using research as my main tool and engage in places with places like Pittsburgh, Wilkinsburg. And just go deeper with my analysis and look for solutions. So, more of the same. Yeah. So, you know, obviously we keep updating our research. We keep finding new insights, but I’m going to keep pressing on fighting for justice.

Eve: [00:35:06] Well, I can’t wait to see what else you do. And I’m certainly going to keep an eye on that Ashoka challenge. It sounds really interesting. Thank you so much for spending time with me today.

Andre: [00:35:16] Hey, thanks for having me.

Eve: [00:35:35] That was Andre Perry, a senior fellow at the Brookings Institute. Andre grew up in Wilkinsburg on the outskirts of Pittsburgh. Once a diverse and thriving neighborhood and now a poor majority Black neighborhood. On his trips home, he can’t help but notice that East Liberty, an adjacent neighborhood and home to Google, is thriving. Meanwhile, Wilkinsburg seems stuck in time. There has been no investment there in decades, and this speaks to the data he has found. Black neighborhoods are valued at 23 percent less than white ones. In Andre’s perfect world, which he is working towards, they’ll be valued the same. You can find out more about this episode on the show notes page at EvePicker.com, or you can find other episodes you might have missed. Or you can show your support at Patreon.com/rethinkrealestate, where you can learn about special opportunities for my friends and followers. A special thanks to David Allardice for his excellent editing of this podcast and original music. And thanks to you for spending your time with me today. We’ll talk again soon. But for now, this is Eve Picker signing off to go make some change.

Image courtesy of Andre Perry/Brookings
Jumpstart desegregation.

April 26, 2021

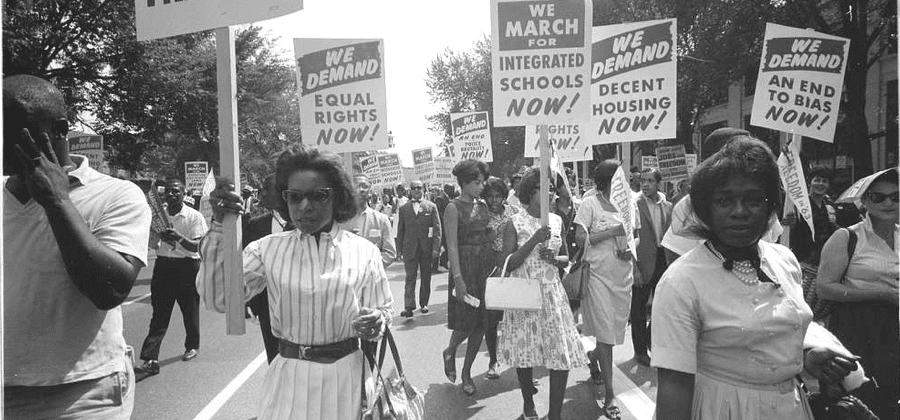
The United States has an ugly history of displacement, exclusion, and segregation which continues to this day. Blacks continue to be denied the same opportunities that are given to whites for affordable rental, home ownership and wealth building. While many may believe that this state of affairs somehow occurred organically, the truth is that Federal, state, and local policies have all led to that displacement and segregation. Those policies continue to undermine the prosperity of minorities, stripping them of wealth and financial stability.

Just a few of the policies that led to catastrophic outcomes for Blacks were:

  • Policies to create outdoor space. In the 1850s thousands of predominantly Black residents were displaced to create Central Park in New York city. And in Atlanta, the oldest subsidized affordable housing project, where 30,000 mostly Black families lived, became Centennial Olympic Park.
  • Policies that discouraged racially diverse neighborhoods. The Federal Housing Administration justified housing discrimination by asserting that if Blacks bought property in white neighborhoods, then insurance values would fall causing loans to be at risk. There was no basis for this rationale.
  • Policies that ‘red-lined’ neighborhoods.  The New Deal, established by Franklin D. Roosevelt to stimulate the economy after the Great Depression, offered home-buying aid to Americans. But color-coded maps of every metropolitan area in the country determined where it was “safe” to insure mortgages. Areas where Blacks lived were ‘red-lined’ to indicate that they were too risky.
  • Policies that encouraged ‘white flight’. Post World War II, the Federal Housing Administration and Veterans Administrations focused on moving the entire white working-class and lower middle-class populations out of urban areas and into single family homes in all-white neighborhoods. This was the beginning of suburbanization and these suburbs came to ring all American cities. And it led to the devaluation of inner city neighborhoods where Blacks lived for many decades.

More recently there has been a shift in housing tastes when life in suburbia, with its gridlocked highways for the morning and evening commute, became less appealing. And so a shift in housing demand has emerged, changing the landscape once again. Wealthy and middle-class people began moving back into urban areas, leading to the redevelopment of previously blighted urban neighborhoods. This revitalization and resulting gentrification exacerbated racial inequality and caused further displacement as Blacks, unable to afford newly gentrified neighborhoods, had to leave once again.

In his book, ‘The Color of Law: A Forgotten History of How Our Government Segregated America’, Richard Rothstein explores the history of housing segregation in the United States. He argues that each of these policies violated the Constitution. Although he recognizes the efforts being made to remedy the situation, he believes we need a more coordinated, new civil rights movement. One focused on housing segregation, to jumpstart desegregation in a meaningful way.

Listen to my conversation with Richard.

Civil Rights March on Washington D.C. from Library of Congress, Public Domain

Andrew loves real estate.

April 21, 2021

Andrew Luong has deconstructed the often lengthy and confusing process of small scale real estate investment, making it accessible to everyone.  He and his partner, Justin, created Doorvest as a turnkey service built entirely online. They help their clients find a property, borrow the funds to renovate it and then sell the finished package to them. Keeping it as simple as possible, they have flat fees and even provide a rent guarantee for the first year. Their track record has allowed them to purchase and renovate properties in poor condition, or in neighborhoods that bankers might not normally like, thus opening the door for new real estate investors who might not have the wherewithal to take those first steps on their own.

Although Andrew began by working in the start-up world, his “squarely middle-class” upbringing led him to decide early on that real estate would be his path to financial security. In his early 20s he started buying and fixing up single-family homes in his spare time. Over just a few years his portfolio grew into the double digits, and he became not just a real estate investor, but a realtor and mortgage loan officer as well.

Over time it dawned on Andrew that the long laundry list of items that comes with purchasing a property, and keeps many people from considering investing in and managing a real estate portfolio, could be rebuilt into an almost frictionless service … bringing real estate investing to everyone. This is what ‘proptech’ is about, and Andrew’s bet is that within a few years most aspects of real estate will be transacted entirely online.

Insights and Inspirations

  • The bigger mission is to democratize access to financial security for all.
  • Andrew mainly sees two kinds of investors through Doorvest, neither of whom has invested in real estate directly before – those recently out of school, gradually building up their savings; and those mid- to late-career, looking towards retirement.
  • Doorvest serves as sort of training wheels for people to get their feet wet, get the exposure, learn about the processes along the way.
  • Andrew thinks most online real estate services are still a bit v1.0. Doorvest is looking towards aggregating far more data and streamlining services, all to empower people to invest in many kinds of real estate “within a matter of clicks.”

Information and Links

  • A quote Andrew lives by: “Your problems never go away, they just change.” It helps him put things into perspective, that no matter how much one “accomplishes,” that satisfaction can really only come from within.
  • Andrew is a fan of “The 4-Hour Workweek,” by Tim Ferriss, which shaped much of his views about work and how to live an optimal life.  (Disclaimer: He spends much more than four hours working per week 🙂 )
  • He is a big proponent of the concept of “work-life integration.”
Read the podcast transcript here

Eve Picker: [00:00:09] Hi there, thanks for joining me on Rethink Real Estate. I’m on a mission to make real estate work for everyone. Real estate can help to solve climate change, can house people affordably, can create beautiful streetscapes, unify neighborhoods and enliven cities. So I’m on a journey to find the most creative thinkers and doers out there. I’m not the only one who wants to rethink real estate. You can learn more about me at EvePicker.com or you can find me at SmallChange.co, a real estate crowdfunding platform with impact real estate investment opportunities open for investment right now. And if you want to support this podcast, join me at Patreon.com/rethinkrealestate, where there are special opportunities for my friends and followers.

Eve: [00:01:16] Today, I’m talking with Andrew Luong, the CEO and co-founder of Doorvest. Andrew loves real estate. Growing up in a lower middle-class family, he decided early on that real estate would be his path to financial security. So he started buying and fixing up single family homes in his spare time. While he honed his skills as an entrepreneur in a variety of start-ups, his portfolio grew into the double digits. He had honed his skills as a real estate investor as well. It dawned on Andrew and his co-founder, Justin, that the long laundry list of items that comes with purchasing a property could be deconstructed and rebuilt into a frictionless process to bring real estate investing to everyone. And so Doorvest was launched to provide a turnkey real estate investment service online. You’ll want to listen in to learn more. If you’d like to join me in my quest to rethink real estate, there are two simple things you can do. Share this podcast or go to Patreon.com/rethinkrealestate to learn about special opportunities for my friends and followers and subscribe if you can.

Eve: [00:02:46] Hello, Andrew, thanks so much for joining me today.

Andrew Luong: [00:02:50] Excited to be here. Thanks for including me.

Eve: [00:02:52] Yeah, I’d heard about your brand new start-up, Doorvest, and I was interested in knowing a little bit more about what you’re doing, what you’re trying to provide.

Andrew: [00:03:03] Right. Our mission as a company is to make, is to democratize access to financial security for all. Kind of where we’re at today is we make real estate investing easy, affordable and accessible to anyone, anywhere, sort of entirely online.

Eve: [00:03:21] So that’s your elevator pitch, right? Right.

Andrew: [00:03:25] Right.

Eve: [00:03:26] But what is the main mode to make? Because there’s so many different ways to make real estate investing easy for people nowadays. What does that mean, Doorvest?

Andrew: [00:03:36] Yeah, I guess to dig into a layer further, we’re essentially a tech enabled turnkey provider. So effectively we begin with our customers. What we’ll sort of learn more about our customers, often everyday individuals that have never participated and owned real estate directly before. We’ll learn more about the individual, kind of what they had earmarked as a down payment. So, what sort of returns or cap rates were they hoping for to what’s their general risk profile? And then with that, we’ll ask for deposits upfront. At that point, we’ll sort of get into what we call production. So, we’ll, based on customer objectives, we’ll then go out into the market. Identify, underwrite and acquire usually distressed, uninhabitable homes. We’ll purchase it. We’ll renovate it and we’ll lease it out. So, the home has sort of completed an income generating from day one. At which point we’ll kind of walk the customer through the mortgage and sort of the third-party transaction process. As the customer closes and takes title, we’ll take on operating. So, we’ll manage the homes for them once they close and take title. Where we position ourselves is that hopefully we will get our customers into again, oftentimes their first rental, hopefully if we perform. So they’re generating the returns that they expected and they like working with our team, hopefully that they come back as they sort of build out their nest egg and portfolio.

Eve: [00:05:09] So let’s back up a little bit. So, what you’re doing is actually helping people buy a piece of property that is going to be income producing for them. And you’re sort of getting rid of all the stress and anxiety of finding the property, renovating it, finding the mortgage. You kind of package all of that up front and turn over to them a fully renovated income producing property, is that correct?

Andrew: [00:05:38] Right. I didn’t think I could have said it better myself, but that’s absolutely correct. The goal is to make it really easy for them because oftentimes our customers are really busy people that have never done real estate before. So that’s sort of the three constraints that our customers see. And I think where we fit in nicely is being busy, being an experienced and oftentimes not having a lot of capital to begin with are kind of the three major points that I think we touch on.

Eve: [00:06:10] Oh, interesting. So, you’re taking the fix and flip out of fix and flip through them.

Andrew: [00:06:15] Right. And giving them the ability to kind of have and lean on a company that has some scale efficiencies. So generally, our appliances are cheaper, our flooring is cheaper, et cetera.

Eve: [00:06:29] Interesting. So what prompted you to launch this?

Andrew: [00:06:33] Right. I’d say it’s sort of my story and or the Doorvest story goes back roughly maybe seven or so years ago. At the time, I was in school studying chemistry and trying to be a doctor. Certainly, you could say that that didn’t work out. But I think I was fortunate and found my way to my first job at a start-up company, ultimately ended up doing okay. And I think I walked away with sort of two learnings. Number one sort of wanted to be spending my waking hours building companies from the ground up, but I really enjoyed the thrill of it, felt like I was okay at it. But secondly, I grew up squarely middle class and grateful that we never had to worry about where sort of dinner was coming from, for instance. But we were certainly by no means financially secure, so experienced firsthand financial security or maybe the lack thereof and its ability to sort of inhibit one from pursuing their dreams. Maybe for my parents, it was the dreams of having a happy family because you’re arguing over sort of the vacation plans. Maybe for others it’s to do something entrepreneurial or work at a non-profit or launch a podcast, what have you. And so, kind of found that that looked for an avenue to kind of generate some income security, build a long-term nest egg for myself. That’s where the two worlds collided. Found my way to real estate investing. Kind of did okay for myself. Built up a small double-digit portfolio for myself sort of nights and weekends while my day was sort of busy working person. And then along the way, through lots of organic conversations, coffees, dinners, what have you, saw others similar to me. And maybe these are folks that traded some stocks on Robinhood and maybe they had a 401k and brokerage account, high yield savings account, et cetera. And we’re thinking about sort of the next progression in assets. Real estate, it’s kind of natural there. But I think and you’ve been in the space arguably a lot longer than I have, but due to sort of the friction filled process along with sort of the capital barrier to entry, weren’t able to participate in sort of America’s number one source of wealth generation. One of those folks along the way was my good friend and now good friend and co-founder, Justin. But as we kind of went through the process together, it kind of dawned upon us that hopefully if we can build a sort of modern, easy way for anyone anywhere to buy and own income generating real estate entirely online, hopefully we could sort of bring this to the masses.

Eve: [00:09:20] Well, you know, you just said something really interesting and that was, you know, access to capital for people who normally can’t access capital. I mean, how does that work? How do you get them access to capital?

Andrew: [00:09:34] A part of it is investing in sort of affordable markets, encouraging our customers and giving them the resources and tools to be able to save and then sort of leveraging that into a market that’s affordable for them. That’s kind of one. I think the second component to that is sort of guiding them through and coaching them through sort of the mortgage financing process. That, in and of itself, is a pretty convoluted process. We hope, longer term to be able to impact sort of the financing process more more directly. But as of right now, we kind of see ourselves as a coach in that aspect.

Eve: [00:10:14] Do you go out and borrow money for the renovations or is that up to your customers at the moment?

Andrew: [00:10:19] We do it. So, we borrow debt as we acquire and manage the renovation.

Eve: [00:10:26] Does that make it easier for them because they are then borrowing or acquiring debt on an already renovated property that a bank can lay eyes on.

Andrew: [00:10:36] Exactly. So that’s one of the ancillary sort of value propositions for us is…

Eve: [00:10:43] That’s huge.

Andrew: [00:10:45] Right? Yeah. So, we’re doing pretty extensive reno. Like for context, we’re doing about 30 percent of the acquisition price as renovations to that number works itself out to roughly 40 or so thousand customers able to roll this into their conventional mortgage. And like you said, the banker is able to sort of have this finished product.

Eve: [00:11:07] Yeah, but I think what I mean by that’s huge is now, you are putting buildings back into circulation that most banks would not probably lend money on, especially not to a first-time fix and flipper. And so that really does expand opportunities for people in a pretty significant way.

Andrew: [00:11:31] Right.

Eve: [00:11:32] Oh, yeah, I was just putting it together because, you know, when we started, I wasn’t quite sure where the impact lies, but I can see the impact really lies here in the ability to help people build wealth. Because, you know, I’ve done this myself. I’ve gone to a bank with a property in a pretty rundown neighborhood and talked about my visions for the property and the bank, scratching their head, saying we definitely don’t want to lend money on this. And then I come back and show them the renovated property and they say, oh, now we get it. So, you are bridging that gap for people.

Andrew: [00:12:12] Right, and I think sort of the second letter to that is sort of the operational component to, again, sort of our target sort of customer and that we serve our folks that are busy, oftentimes with a demanding sort of day job and our folks that sort of haven’t done much real estate investing directly. So, we kind of serve as sort of training wheels for them to get their feet wet, get the exposure, learn about the processes along the way. And then the second component is that we do the heavy lifting for them to kind of have that finished product.

Eve: [00:12:51] So where are you doing this?

Andrew: [00:12:53] Right, we’re focused on Texas as of right now, it’s sort of an operating market.

Eve: [00:13:00] And how many times have you done this for customers so far? If you’ve been… you launched when, in the middle of the pandemic?

Andrew: [00:13:09] I’d say more or less we were born out of  Covid. So, I’d say Justin and I were sort of working out our best early last year kind of got started, maybe March or so. So that’s squarely at the beginning of the pandemic. And yeah, we’re at sort of low, sorry, mid double digits, sort of homes transacted. I don’t have the numbers top of mind, but we’ve been growing steadily. It seems like customers, kind of what we have to offer has been compelling to customers. It’s whether, the question then lies, how do we do this at sort of greater scale, serve more customers?

Eve: [00:13:52] Right. Right. Do you have repeat customers yet?

Andrew: [00:13:55] We’re soon to. Actually, we have a couple early ones, and we actually have a handful of them that are expected to buy their second home through us this month. So that’s sort of validation of our model and we’re really excited to have that and see that.

Eve: [00:14:14] That is exciting. So what do you, what do your customers generally look like? Are there any anomalies or is it pretty squarely one group of people?

Andrew: [00:14:25] Right. So as of right now, there’s two core groups of Doorvest customers. So, number one is busy working person, maybe call it five years or so out of college. They’ve been gradually building up their savings and are kind of thinking about real estate for the first time ever in their lives. That’s sort of one group. The second bucket is, I would call them mid to late career. So again, busy working person. Maybe they own their primary. Maybe they’ve got a couple of primaries over the course of their career or looking forward towards retirement and thinking about income streams and nest egg and what have you. They’ve never invested in real estate directly ever. They’ve always been sort of intrigued by the idea, but never had a vehicle or the time to do it themselves. And so Doorvest’s kind of serves as a retirement vehicle for them.

Eve: [00:15:26] Interesting and do you have a second market in mind already or you’ve got plenty to do in Texas?

Andrew: [00:15:34] We have plenty to do, but we are eying a number of other markets. I think market number two, whenever that, it’s a matter of time, don’t have sort of a concrete timeline. But at some point, we will expand into our next market. I think the way that we’re thinking through that, number one leads with customer demand. So, what are our customers asking of us? And what would sort of the early hypothesis being? It’ll be either a market similar to where we’re at in Texas or maybe a more yield focused market. Call it a Memphis, Tennessee or so, or maybe a sort of growth market, call it a Phoenix or so. Yet to be determined. Hopefully in the coming decades we end up in all of those markets and hopefully more. But we have plenty to do at this point.

Eve: [00:16:28] Yeah. So, you’re building a technology around all of this, right?

Andrew: [00:16:33] Right.

Eve: [00:16:34] And what does that look like? What do you have to build? What have you built so far?

Andrew: [00:16:38] Right. I think we have a long way to go. I think kind of where we’ve gone so far as customers are able to buy homes entirely online, leveraging the data sources that are either proprietary to us or data sources that we as an organization are able to access. Along with lots of sort of ways to analyze the home online, whether it be integrating Google Maps Street View, so they’re able to to do a brief walk around the neighborhood or whether it be having Mattermark reports, so they’re able to walk through the house. Whether it be crime or school data, et cetera. I see our work as sort of aggregating various data sources. I think that the first generation of sort of real estate companies, such as the Zillows and the Redfins of the world, brought a lot of real estate online. I think I see it as our sort of job is to organize that data, sort of make sense from it in a digestible, sort of actionable way. To kind of where we’re at. Today’s customers are able to buy a home entirely online. It takes many, many clicks, many emails, and many phone calls over time. Our sort of aspiration as a company is how do we get it to the point where an individual can be anywhere earning any amount of money and able to participate in America’s number one source of wealth within a matter of clicks. I think we have a long way to go, but excited about sort of the progress we’ve made so far.

Eve: [00:18:17] Yeah. So, I have to ask you, how many of your customers have gotten off the sofa and actually gone to look at the property they’re going to buy?

Andrew: [00:18:25] Right. Low single digits. Yeah. So, we’ve added a number…

Eve: [00:18:31] About 60, 50 percent, 40?

Andrew: [00:18:34] Sorry, sorry. I think it’s about five percent or so. So, the number is pretty low. The majority of the folks that we’ve served have sort of leaned on us, given sort of our business model and where we positioned ourselves to kind of do the heavy lifting for them.

Eve: [00:18:53] Interesting. So, then you’re also operating as a property manager and…

Andrew: [00:18:59] Right.

Eve: [00:18:59] So what does your team look like?

Andrew: [00:19:02] Right. So, I guess in terms of the entire team as of today, where we’re 17 folks, small but mighty, I think, and sort of gradually growing. Spread across sort of the many different facets of the business. About a third of our team is on what we call success, which is sort of property management, traditional property management. I think with the twist, yes.

Eve: [00:19:30] The traditional property management can be labor intensive and frustrating.

Andrew: [00:19:36] Right, right.

Eve: [00:19:37] Yeah. Yeah. So how do you hope to scale? Have you, must have thought about that as a start-up.

Andrew: [00:19:45] Oh yeah. Lots, lots of thoughts about that I think sort of beginning with our mission, but really to democratize access to financial security for all. As of right now, we’ve made it accessible to anyone, anywhere with roughly thirty thousand as a down-payment is able to participate in real estate directly, entirely online. I’m proud of that. But I think that still means that we have a long way to go to sort of make real estate accessible to anyone, which means sort of driving sort of the capital barrier to entry down. I think over time, our aspiration is to make it so anyone can participate in real estate with call it 30 thousand, maybe 20, maybe 10, maybe five, maybe 500, maybe 100. Again, I think we have a long way to go to get there.

Eve: [00:20:37] Oh, interesting. Yeah, yeah, yeah. So wow, that’s quite an enterprise, Andrew.

Andrew: [00:20:46] It’s a lot of work. And I’m fortunate that our team is really sort of thrilled and excited and cares deeply about sort of what what we’re hoping to build for the world. Again, I certainly see that we have a long road ahead, but I’m confident if we’re able to succeed, I hope we can impact the lives of many, many people for the better.

Eve: [00:21:10] Because it’s really three businesses in one. I mean, the property management business, you can have a fix and flip business, or you can have a technology start-up. Right?

Andrew: [00:21:19] Right. That it’s funny that you say that you mentioned the three businesses and one, this is something that I talk about with internal and external, whether it be our investors or our future investors or partners, et cetera. But effectively, we’re gluing three businesses into one and three very complex businesses. I think if we succeed, we offer our end users sort of the, a really nicely packaged, really nicely packaged experience.

Eve: [00:21:51] I could see you adding in the fourth, and that’s real estate brokerage. Your missing…

Andrew: [00:21:57] That. That’s right. We’ll get there, I think.

Eve: [00:22:00] You will. I’m pretty sure you will. So so what’s the biggest challenge you’ve had?

Andrew: [00:22:08] Right. I think it evolves. I remember I was talking to Justin a little bit back, and I was like Justin, it feels like things we’re encountering more challenges than ever before. Is this because we’re not good at kind of what we’re doing? And somehow ,we’re facing more challenges. And as we’re talking, I think it kind of surfaced that as a small business that’s trying to be a bigger and bigger, more impactful business, the way that we get there is by unlocking ourselves a new set of challenges. That’s a long-winded way of me saying I think the challenges evolve. If you ask me four weeks ago, maybe I would have said the ability for us to consistently raise the real estate debt to be able to fund these transactions. Thankfully, I think we’re kind of past that now. As of right now, I think I mean, this might be outside of our control to a certain degree, but sort of the macro, as we’re seeing in the real estate industry. So, lots of competition, which makes inventory really tough, lots of delays, supply chain delays. So it feels like every step along the way is adding two or three days, which amounts to really long delayed timelines for our customers, etc.

Eve: [00:23:31] We’re experiencing that ourselves. Supply chain delays seem to have gotten worse in the last, I think, in this year than they were last year somehow.

Andrew: [00:23:40] Right. I’d love to see some numbers behind it, but this is certainly what we’re feeling internally, too.

Eve: [00:23:45] Yeah, it’s almost like people are trying to build their businesses back up and they’ve got to start from scratch. They’ve got to be reborn. We can’t get contractors to perform, yet, but that will go away, surely.

Andrew: [00:24:00] That’s a hope. Yeah. And I want to be sort of intentional and careful about us sort of having this hope and hopefully it’s validated. It sounds like I mean, based on conversations like our conversation right now and others that I’ve had, it sounds like this is a matter of time, in which case I feel good about that. But everything from appraisal delays to appliances taking a week longer to flooring taking a little bit longer, etc. Like that kind of adds up for our business.

Eve: [00:24:31] What part of the business do you love most of?

Andrew: [00:24:36] There’s many areas. Honestly, I’d say number one is, so I came from sort of the sales and business development background. What that means for us is sort of working with our customers who are oftentimes folks that have never sort of participated in real estate, nor did they think that they were able to right now. So, seeing and hearing their stories, whether it be, hey, my wife and I have been thinking about how we’re going to supplement our retirement and our 401K based on our number crunching just isn’t enough. And we hope that if over the course of the next 10 or so years, if we buy a handful of rentals and kind of get that paid off through Doorvest. Like, we have this sort of extra layer to our income streams, et cetera, and you all make it so easy for us to do this while we could still focus on our busy lives, which is our jobs. We both have jobs and our children who we care deeply about. Like hearing those stories and spending time with sort of our customers, it never gets old. I, believe as we go from mid double-digit customers to hopefully triple and quadruple etc. customers, I believe this will stick with me. So that gets me really excited.

Eve: [00:26:01] So what’s your very big, hairy, audacious goal?

Andrew: [00:26:07] Right. Our hope is to impact the lives of, I mean, every American, given the fact that we’re interfacing with busy working people, we’re interfacing with our residents, et cetera. I think sort of in the nature of the space that we’re in, we impact and touch a lot of lives, even beyond sort of these direct folks that we’re working with day to day. We’re impacting the lives of our general contractors and our vendors and our partners, et cetera. The big audacious goal, I think, is to sort of be cognizant of the position that we’re in and driving sort of win-win solutions across the board.

Eve: [00:26:53] Well, this sounds some really amazingly exciting, and I can’t wait to see where you are in five years from now. You’re very young. You just starting out. It seems like you’ve made big strides already. So, congratulations. And I look forward to hearing more.

Andrew: [00:27:09] Thank you. Yeah, I appreciate it. Sometimes it feels like we’re just getting started. And I certainly think that’s the case. I think if we kind of all align ourselves about what we care the most about in this world, I hope and I think we can do sort of amazing things for the world. So, hoping to stay in touch as we rebuild away.

Eve: [00:27:36] That was Andrew Luong of Doorvest. Andrew and his partner, Justin, have deconstructed the often lengthy and confusing process of small-scale real estate investment, making it accessible to everyone. Their turnkey service is built entirely online. They try to keep it as simple as possible with flat fees and even providing a rent guarantee for that first year. They help their clients find a property, borrow the funds to renovate it and sell the finished package to them. Their track record allows them to purchase and renovate properties in poor condition or in neighborhoods that bankers might not like. Opening the door for retail investors who might not have the wherewithal on their own. We’ll be watching Doorvest as it grows.

Eve: [00:28:38] You can find out more about this episode on the Show Notes page at EvePicker.com or you can find other episodes you might have missed, or you can show your support at Patreon.com/rethinkrealestate, where you can learn about special opportunities for my friends and followers. A special thanks to David Allardice for his excellent editing of this podcast and original music. And thanks to you for spending your time with me today. We’ll talk again soon. But for now, this is Eve Picker signing off to go make some change.

Image courtesy of Andrew Luong/Doorvest

Housing in the middle.

April 12, 2021

Zoning in America. It’s a vast set of regulations which determines where and what you can build, how high and how close to your property line your building can be, how much of your land you can occupy, how much parking you need to provide and what type of tenant can occupy your property.

Once upon a time nuisance laws were the only way to regulate building disputes, with a judge deciding the outcome. In the early 20th century as cities grew and buildings became larger and taller, this process became unwieldy. The Equitable Building in New York changed all that. Completed in 1915 it was said to cast a 7-acre shadow over surrounding buildings and became the catalyst for the first comprehensive zoning code passed by the city of New York in 1916.

Skip forward one hundred years and we might just be back to where we were in the early 20th century. Zoning has become a behemoth. Many cities are using 50-year-old zoning codes which have had many bandaids applied to them over time, making them out-dated, complicated and far too long. Most importantly, over the last 50 years for the most part zoning has not changed sufficiently to reflect the sometimes rapid changes in our cities. There’s a shift in how people want to live. Sprawling suburbs no longer offer the kind of lifestyle that many Americans are looking for. They want a more sustainable lifestyle in a walkable urban context. And what’s missing is the housing typology, in between single-family detached and large apartment complexes, that’s required to fulfil this need. 

The idea of this ‘missing middle housing’ was framed by Daniel Parolek, architect, urbanist and the founder of Opticos Design. Missing middle housing was born just as the critical absence of affordable housing was becoming a major planning issue for cities nationwide. As a result, Daniel has become a high-profile advocate for zoning reforms that would allow for ‘the right kind of density.’ More people, less parking, walkable neighborhoods and broader demographics.

Listen in to my conversation with Daniel.

Image from Pixabay

The JUST Podcast.

April 5, 2021

The JUST Podcast tells the stories of the people working to build thriving communities rooted in justice.

In this episode, Derigging the Real Estate Game (Season 3, Episode 3), Eve Picker, founder and CEO of Small Change, is interviewed by JUST co-hosts Jes and Rob. Eve shares insights on the nature of exclusivity in real estate, and what led her to pursue Small Change.

You can listen here or wherever you stream your podcasts! 

Image from The JUST Podcast.

Just is powered by Coastal Credit Union & the Cap

« Previous Page
Next Page »

Primary Sidebar

sign up here

APPLY TO BE A PODCAST GUEST

More to See

The Seven

August 29, 2025

Real estate and women.

February 26, 2025

Oculis Domes.

February 25, 2025

FOLLOW

  • LinkedIn
  • RSS

Tag Cloud

Affordable housing Climate Community Creative economy Crowdfunding Design Development Environment Equity Finance FinTech Gentrification Impact Investing Mobility Offering Opportunity zones PropTech Technology Visionary Zoning

Footer

©rethinkrealestateforgood.co. The information contained on this website is for general information purposes only. Nothing on this website is intended as investment, legal, tax or accounting strategy or advice, or constitutes an offer to sell, solicit or buy securities.
 
Any projections discussed or made may not be accurate and do not guarantee a specific outcome. All projections or investments are subject to risk due to uncertainty and change, including the risk of loss, and past performance is not indicative of future results. You should make independent decisions and seek independent advice regarding investments or strategies mentioned on this website.

Recent

  • Vacant Upper Floors: Unlocking Downtown Housing
  • Podcast hiatus.
  • Pop City: Changing the Conversation
  • The Mulberry
  • Mount Vernon Plaza

Search

Categories

Climate Community Crowdfunding Development Equity Fintech Investing Mobility Proptech Visionary


Copyright © 2026 · Magazine Pro on Genesis Framework · WordPress · Log in