• Skip to main content
  • Skip to secondary menu
  • Skip to primary sidebar
  • Skip to footer
  • Home
  • About Us
  • Say hello
Rethink Real Estate. For Good.

Rethink Real Estate. For Good.

  • Podcast
  • Posts
  • In the news
  • Speaking and media
    • About Eve
    • Speaking requests
    • Speaking engagements
    • Press kit
  • Investment opportunities

Investing

Small versus big.

May 11, 2020

There’s a history to small-scale development. It’s what we did for centuries until industrial modernism brought large-scale development to our cities.

Large-scale development

The scale and cost of large developments falls into the realm of large-scale developers, and not always good ones. They have been the protagonists in the rapid transformation of our urban environment. Large-scale developments have often had disastrous impacts on local communities and small businesses and have led to the decline of diversity and vitality in many neighborhoods.

Some solutions

There have been many studies into how to tackle the problems that large-scale developments have caused. One important step is to involve the locals. Engaging the community plays a fundamental role in identifying negative impacts and understanding how a development will impact its surroundings.

Most important is the relationship between social activities and the urban space. Solutions might include a mix of old and new buildings to keep some of a neighborhood’s character, small blocks where neighbors might get to know each other, a mix of residential and small business to bring people out into the streets and public space to create a local focus and help promote vitality.

Back to small-scale

Large-scale developers have many resources to tackle zoning codes, financial institutions and all the other complications of development. But small-scale development, buildings with less than 20 units, has become a lost art. How do you build a small building in the place you love? Jim Kumon co-founded the Incremental Development Alliance with the goal of “resurrecting the small developer.” The Alliance provides training and technical assistance to anyone interested in tackling those small-scale projects that make your neighborhood great.

To learn more listen to my full interview with Jim Kumon

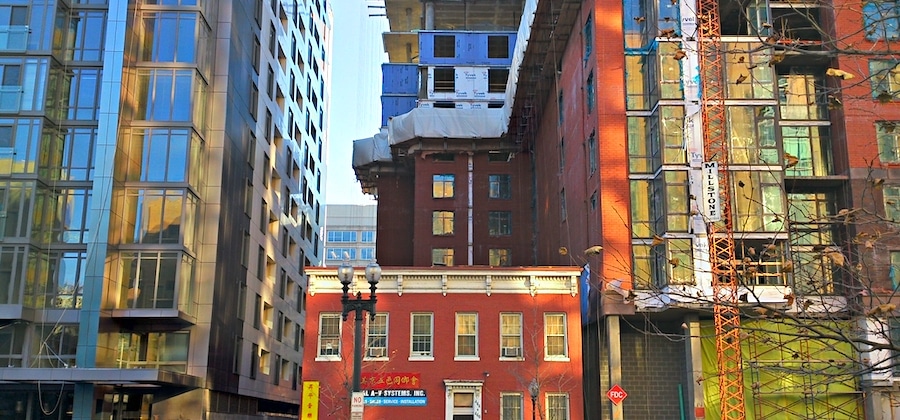
Image by Peyton Chung / CC BY-2.0
Smart money is on impact.

April 27, 2020

Simply put, impact investing is the practice of using investment dollars to generate positive social or environmental impacts in addition to offering a competitive financial return. The idea that we can do far more with our money than merely reap monetary dividends is important, and has grown popular recently, steadily gaining traction with investors, whether small or large. As we increasingly wrestle with broad and difficult societal issues like affordable housing and climate change, issues that will impact the lives of millions of people, so too are we learning that impact investing can be an essential part of the solution.

Impact investing does not mean giving up on a good financial return. We’ve long known that what’s good for people and the environment is ultimately good for businesses and economic growth as well. And the competitive returns that investors are getting through impact investing only serves to reinforce this. This reality is highlighted by the fact that every day more institutional investors are committing an ever-growing pool of their funds to impact investing. As an example, one of the largest financial companies in the U.S., Prudential, has an Impact Investment division that should serve as a model of impact investing at the institutional level.

Catalytic and creative

In their Impact division, Prudential Financial has built a distinct portfolio of investments with the goal of both making money and having a social impact through each of those investments. The focus of this portfolio is specifically on projects that can lead to catalytic change. These investments can be higher risk and are often declined by their traditional portfolios.

Prudential has invested about $1 billion dollars into impact investments. Typically, when an institutional investor reaches a milestone like this, they’ll aspire to the goal of growing that portfolio, to say $10 million. Ommeed Sathe, the Vice President of Impact Investing at Prudential and engineer of their impact portfolio, thinks that’s the easy option to take. Instead, he’d like to push the envelope and focus on growing impact by seeking ever more catalytic and creative projects. These might include minority developers, in neighborhoods that have seen little investment or building-types that defy the norm. This is an encouraging and unusual goal for a large investment fund that hopefully will inspire other institutional funds to follow suit.

The portfolio overseen by Ommeed and his team is currently focused on both real estate and business investments, all of which would be considered socially conscious or beneficial. On the business side, companies have a social purpose, are financially inclusive, do work to retrain and reskill our workforce, and are working on sustainability. For example, in Washington D.C., they helped fund improvements to green infrastructure and create the first tradable stormwater credits, not unlike carbon tax and trade mechanisms, but done at the local level. Real estate investments include affordable housing, redevelopment and brand-new development projects that have the potential to transform the communities in which they are based.

While impact is critical, the driving goal for Prudential is to invest to make a return. These investments are meant to be competitive. But still, the focus of their impact investments portfolio is to invest in assets that more traditional portfolios would normally not invest in, not normally take a risk on.

The takeaway

It is groundbreaking for a large company to invest in this way, and further, to want to expand their reach even more. There is something to be said for the scale of change that institutional dollars can make. If investment funds push more capital into large and necessary projects such as affordable housing and mixed-use developments, especially in communities that need it most, there will be enormous benefit to everyone. And as these funds become more comfortable taking part in catalytic projects, they will discover a wide swath of investment opportunities that they may have previously overlooked. Investing for impact at this scale can have an impact we haven’t imagined before.

Listen to my full interview with Ommeed or go ahead and make your own impact investment.

Image by Rajkiran Pericherla / CC BY-SA 4.0

Public space. The heart of the city.

March 30, 2020

There are numerous factors that city planners, politicians, developers and designers consider when planning cities; from infrastructure to transit to the creation of residential, commercial and retail space, all to draw new businesses and residents. But often the last thing to be considered, and yet perhaps the most critical component in any city neighborhood, is public space. Parks, plazas, walking and bike paths and even wide, strollable sidewalks all play an integral role in connecting communities and giving people a sense of belonging.

In a recent podcast interview with Eve, former Pittsburgh Mayor, Tom Murphy, reflected on some of his administration’s big wins in revitalizing the city of Pittsburgh, as well as some missed opportunities. In his post-mayoral career, Mayor Murphy regrets not putting public space front and center.

Turnaround mayor

Tom Murphy served as Pittsburgh’s major from 1994 to 2006, a turbulent and transformative time for the city. He took over the reins of the city when it was decimated by a loss of the steel industry and out-migration of over 50% of its population. During his tenure Tom created a $60 million development fund to jump-start development in abandoned neighborhoods, built two new waterfront stadiums, and developed many miles of river trails. At the end of his tenure, he had presided over a remarkable urban comeback story, and the city has been transformed in a myriad of ways.

At the heart of Murphy’s plan to revive Pittsburgh was the purchase of 1,500 acres of land for new development. This gave the city a chance to create effective public-private partnerships with developers to restore struggling parts of the city, all the while luring new businesses to the region and encouraging others to stay and grow.    

Planning for public spaces

Murphy strongly believes that a sense of “place is everything,” and can have a huge impact on the quality of peoples’ lives. He notes that in addition to the large-scale developments his administration sponsored, they were also able to also rebuild all of the city’s 100 or so neighborhood parks, both small and large, all while involving the local communities. But he is quick to add, that although their instinct was right, they should have gone further, expanding the city’s park system instead of just rebuilding it. Some neighborhoods that have long lacked communal gathering places would have benefitted from the creation of wonderful new plazas.

Reflecting on his experiences in Pittsburgh, and as a frequent visitor to cities all over the world in his role as a Senior Fellow at the Urban Land Institute, Tom has come to believe that an even a stronger sense of community can be encouraged through the use of public space, whether it’s a playground or a park. He wonders how you can thoughtfully connect people in a neighborhood so that they feel a sense of belonging to the place. He believes that “if people feel rooted in their neighborhood, … they’re willing to put up with a lot of problems if they see themselves and others committed to wanting to making it better.”    

Getting communities invested

Public spaces are crucial for building successful cities. They help to bring communities together and invest people in their neighborhoods, regardless of background or income. Amidst lucrative development plans, it can be easy to overlook the importance of public space, but as Murphy notes, city government and local communities can and should work in partnership with developers to make sure public space is at the forefront of every new development and planning project.      

Listen to the full interview with Tom Murphy to hear more about his vision for public spaces and the role that public space plays in building better cities.      

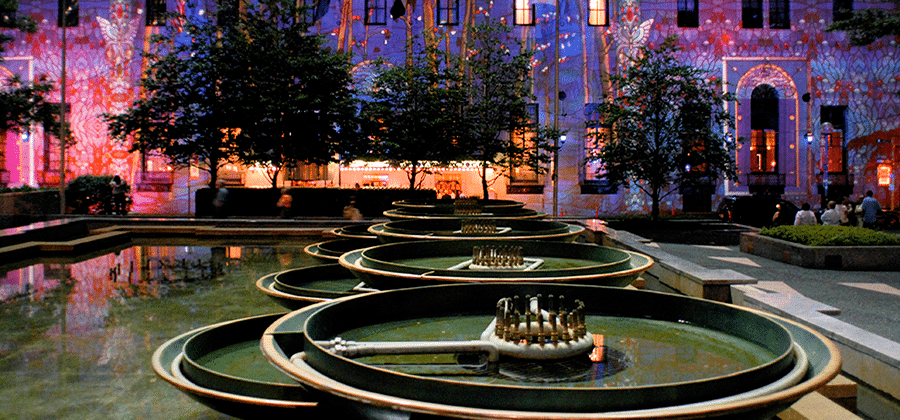
Artlumiere light projections ’09 courtesy of Jonathan Greene

Democratizing investment. A huge step forward.

March 25, 2020

Mark Roderick describes himself as a very “boring” corporate and securities lawyer, but he’s not. Since the JOBS Act of 2012, Mark has spent all of his time in the investment crowdfunding space. Today he is one of the leading crowdfunding and fintech lawyers in the United States. Mark writes a widely-read blog, which offers a wealth of legal and practical information for portals and issuers. He also speaks at crowdfunding events across the country, and represents industry participants across the country and around the world.

Most recently Mark launched a new firm, Lex Nova Law, a boutique corporate law firm representing crowdfunding, fintech, startups, blockchain and cryptocurrency along with more traditional legal sectors.

Along with the rest of us in the crowdfunding industry, Mark applauds the SEC for its proposed upgrades to all of the online offerings: Rule 504, Rule 506(b), Rule 506(c), Regulation A, and Regulation CF. In this podcast we focussed on Regulation CF, which promises to turn into the little engine that could when these changes take effect.

“These proposals are great for the Crowdfunding industry and for American capitalism. They’re not about Wall Street. They’re about small companies and ordinary American investors, where jobs and ideas come from” says Mark.

The proposals and the reasoning behind them take up 351 pages. You can find an SEC summary here, or the full text here. Some of the key highlights for Regulation CF include much expanded investment limits for both accredited and non-accredited investors, and an increase in the maximum amount an issuer can raise in any one year from $1.07 to $5 million.

Insights and Inspirations

  • Mark believes the latest round of changes to the crowdfunding rules will bring some fundamental changes to the industry including higher quality deals.
  • As the deals get better, so will the industry grow, and more investors join in.
  • He expects to see changes in the physical landscape in just 5 years as these rules begin to have a far-reaching effect.

Information and Links

  • Read the entire 351 pages of proposed changes to the online crowdfunding rules here and a more digestible summary here.
  • Mark’s investment crowdfunding blog provides a wealth of information for those in the industry.
Read the podcast transcript here

Eve Picker: [00:00:08] Hi there. Thanks so much for joining me today for the latest episode of Impact Real Estate Investing.

[00:00:14] My guest today is Mark Roderick, founder of Lex Nova Law and one of the top online crowdfunding experts in the country. I asked Mark to join me today to discuss the very exciting changes proposed by the Securities and Exchange Commission to regulation crowdfunding. In case you haven’t heard of it, regulation crowdfunding, or Reg CF, is the securities regulation that is really the first step taken by the S.E.C. towards democratizing investment. The additional changes proposed will give this regulation real legs.

[00:00:57] Be sure to go to EvePicker.com to find out more about Mark on the show notes page for this episode. And be sure to sign up for my newsletter, so you can access information about impact real estate investing and get the latest news about the exciting projects on my crowdfunding platform, Small Change.

Eve: [00:01:18] Hello, Mark, it’s delightful having you on my show.

Mark Roderick: [00:01:21] Well, thank you very much. It is delightful sort of being there.

Eve: [00:01:25] Very good.

Mark: [00:01:26] Virtually.

Eve: [00:01:25] Just sort of. Yeah. Okay. Today, we’re going to talk about raising equity online, which is a pretty wonky subject, but you and I like it. And raising equity online is also known as equity or investment crowdfunding. You said these proposals are great for the crowdfunding industry and for American capitalism. They’re not about Wall Street. They’re about small companies and ordinary American investors, where jobs and ideas come from. And you were referring to some proposed changes to equity online raising funds. And according to the S.E.C., a majority of entrepreneurs and emerging businesses raise capital using an exempt offering framework under the Securities Act. And they raise everything from seed capital for new businesses, to funding growth on the path to an initial public offering, and, also, raise equity for real estate. So, I wanted to talk about the rule changes and why you think they’re so great.

Mark: [00:02:35] Well, okay. Big question and a big, big topic. I mean, maybe I’ll just start at the granular level and then kind of work backwards. If you are in or around the existing industry, And I’m going to call it the Title 3 industry or the Reg CF industry, as opposed to what we might call the Rule 506(c) accredited investor industry. The accredited investor industry in real estate is super-healthy. People are raising a lot of money and platforms are profitable and all kinds of wonderful things are going on. In contrast, the Reg CF world, the industry, it’s sort of, you know, like when you cross the railroad tracks and crossed into the less affluent part of town. It’s a very, almost, I don’t want to get too hyperbolic, but, you know, it’s a little bit of a desolate landscape.

Eve: [00:03:41] Oh yes.

Mark: [00:03:41] It’s very difficult to make money for funding portals, and it’s a vicious cycle as opposed to a virtuous cycle. So, it’s hard to make money. Very small companies with very limited resources are applying because of the limits – we can only raise up to a million dollars a year, and in real estate, in particular, that’s not very much money. And that leads the portals, the funding portals, too many of them, not yours, I should say, but too many of them have adapted to that situation. You know, you’re trying to squeeze money out of people who don’t have any money and have led to a lot of shortcuts, and what I called gimmicks, and that is a vicious cycle because investors, who are not dumb, see that, they see that’s what’s going on. You know, they just ignore the entire industry. And that means that high quality companies are that much less likely to try to use Reg CF. And it has been a vicious cycle.

Eve: [00:04:46] Just backing up one minute. I think some of our listeners maybe not familiar with Reg CF or regulation crowd-funding. So, I just feel like I need to fill in a little bit. Regulation crowdfunding and other online crowdfunding rules grew out of the Jobs Act of 2012, and the intent was really to move online crowdfunding for donations to crowdfunding for investment, right? And so regulation crowdfunding is the rule that lets anyone over the age of 18 invest, but really kind of limits how much they can invest, and how much the company raising money can raise. Those limits, I think, have been the real stumbling block, right?

Mark: [00:05:31] Yeah.

Eve: [00:05:32] So, this has translated into smaller offerings, just like you said, which these funding platforms, which are very heavily regulated to use that rule, it means that they can’t make a lot of money. And that’s kind of where you left off, right?

Mark: [00:05:50] That is exactly right.

Eve: [00:05:52] The new rules, which you seemed very excited about last week, I think, will make some big changes in that landscape.

Mark: [00:06:01] Yeah. They will make a couple changes that are, I think, taken together, just gonna be very, very important and are really going to, to continue that bad metaphor I was using, really revitalize the Regulation CF neighborhood. These are the two most significant changes. As you said in your overview, Regulation CF or Title 3 – those are interchangeable names for the same set of rules – limit very severely how much each investor can invest. And the idea here was to protect widows and orphans from all the shady entrepreneurs out there. But even if the widow or orphan wants to invest his or her entire net worth into a questionable company, the Reg CF rules won’t allow that. To the contrary, they allow only very small investments. And that means that when you’re trying to raise money in Regulation CF, you have to find lots of investors, because each of them can only contribute a very small amount. And, you know, that’s hard. Marketing is hard.

Eve: [00:07:21] It’s very hard.

Mark: [00:07:22] It is also inconsistent with other S.E.C. rules, which in general allow accredited investors to invest as much as they want. One of the fundamental concepts in U.S. securities laws since the 1930s has been that rich people can take care of themselves. They don’t need the government to protect them. And so the term ‘accredited investor’ is sort of a stand-in for rich people. All of the other S.E.C. rules, really, allow accredited investors to make bad decisions, you know. An accredited investor can invest his or her entire network in a single deal. And people have noted, since the outset of regulation crowdfunding, that the regulation crowdfunding restrictions are inconsistent with that general concept. So, one of the changes just made by the S.E.C., or proposed, is that, what do you know, accredited investors will no longer be subject to those severe limits. In fact, they won’t be subject to any limits. So, now if you can attract some accredited investors, you know, you can get people to write big checks. So, that’s an important change. Really important change.

Eve: [00:08:40] Yeah. Yeah. I mean, I’ll give one example that has impacted us. We have quite a few account holders or investors who are accredited by definition based on their net worth. And they have very healthy networks, but they’re retired and they own their houses and their income is maybe below 100,000. And under the regulation crowdfunding Reg CF rules, one of these investors was limited to investing 4,000 a year under Reg CF. But as an accredited investor, she can invest however much she wants. That’s how weirdly bad the rule is right now.

Mark: [00:09:20] Yeah. And just to take that one person, I don’t know how much of a check that person might write, but let’s say it’s, you know, 25 or 50,000 dollars, which is not an unusual investment in the Rule 506(c) world. So ..

Eve: [00:09:34]  Yeah.

Mark: [00:09:35] … she goes from even conservatively …

Eve: [00:09:38] She couldn’t be bothered investing 4,000. She might be interested in 15,000 or 20 or 25 but not …

Mark: [00:09:44] Yeah.

Eve: [00:09:44] Yeah.

Mark: [00:09:45] So, it doesn’t take many of her, you know, the difference between four and say, even conservatively, 25. Those numbers add up quickly. That change in itself was significant. But, in addition, the second change is they’ve raised the limit from a million dollars to five million dollars. And that means bigger companies, companies with more revenue, more products, more services, more scale. Bigger companies can now start using Reg CF. Yeah, I mean, you know, Eve, that a million dollars is not very much in the real estate world. Five million dollars really is a lot. Lots and lots and lots of deals are done with equity of two or three or four million dollars. So, it vastly expands the number of ticket holders who are allowed to attend this event. And then, when you put those two together, you know, now we can do a three million dollar raise where we can raise as much as we want from accredited investors. That, suddenly, becomes an extremely viable business. And that’s the point that funding portals will now be able to make money. In fact, they’ll be able to make significant amounts of money. You know, that’s like, again, going back to that metaphor, that is pouring a lot of money into that neighborhood. And you’re going to see, in my view, just a fundamental change. You’re going to walk through the streets and say, oh, that used to be a dilapidated building. It looks nice now. And so on and so forth. And you’re going to see better business practices from the portals. I believe you’re going to see much higher quality offerings on those portals. In fact, you’re going to see websites that were formerly only in the Rule 506(c) world who had shunned Regulation CF. You’re going to see those companies getting their portal licenses and saying, hey, we can now expand our investor clientele at very little cost. You know, we’ve been marketing only to Rule 506(c) accredited investors. Now we can market to everyone. Why not?

Eve: [00:12:10] Maybe the answer, response to why not, is the regulation that is attached to, being a funding portal, and not to 506(c).

Mark: [00:12:20] Yes. I mean, it’s certainly an impediment. I mean, you’ve been living in this world for the last five years and the regulation can make you pull your hair out. But the business opportunity, it seems to me, is … the landscape just changed completely in my view, you know, I … within the last three weeks before these proposals came out someone called me, a company, you know, we want to be a funding portal. And I tell them, because I try to be very straightforward with anyone, you know, you’re not going to make any money. It’s a funding portal.

Eve: [00:12:55] Right.

Mark: [00:12:55] You know, you want to go, have to expand, vertically integrate. But it’s a very, very difficult business. And that was advice I’ve given in the last two weeks. You know, I’ve had people contact me since the proposals, and it’s totally different advice. This is a real opportunity.

Eve: [00:13:13] Yeah, yeah, yeah. Interesting.

Mark: [00:13:14] I mean, how do you see it affecting your business? You’re in the business.

Eve: [00:13:19] The thing you haven’t touched on yet is, there’s a couple of things that really matter to me. And one is, yes, the fact that accredited investors can invest whatever they want really matters, because I no longer have to offer side-by-side offerings which are very complicated and time-consuming. So, by a side-by-side offering, I mean a Reg CF plus a 506(c), at the same time. So, that can go away. I think the fact that the investor limits have been turned upside down is huge. The fact that now an investor can invest the greater of their net worth or income is absolutely enormous for my crowd. And then I think the single purpose entity rule, which we haven’t talked about yet, is huge. Until now, if you’re going to use a regulation crowdfunding offering type, your investors must invest into the actual deal, which is often not the way that real estate deals work. So, being able to collect a group of investors in a single purpose entity to invest into a project, or a series of projects, is a very big deal. And I’ve been talking to one institutional developer who was really pulling his hair out and trying to figure out how to make Reg CF work for the community he’s interested in using it for, and that particular change makes the whole thing possible. There’s more, I’m sure, testing the waters. I mean, we haven’t talked about all these things, Mark. So, the marketing rules around Reg CF are stifling. And so I want to learn more about what does it mean now to be permitted to have a demo day or to test the waters to, you know, just show the deal before you actually register it with the S.E.C.? I think all of those things really matter.

Mark: [00:15:13] Yeah. There are some other important changes, including, as you say, this so-called testing the waters. We used to have this ridiculous rule, really, that subjected, you know, these tiny Title 3 issuers to more stringent rules, you know, then the largest companies. It was crazy.

Eve: [00:15:35] Yeah.

Mark: [00:15:36] If you were talking, some developer was trying to create this little project, you know, you had to tell that person, you can’t even whisper that you are considering a Title 3 [offering] … You can’t tell anyone, you know, don’t tell your wife. And it was just this ridiculously restrictive rule. So, that is now going to be swept away. And basically, for all intents and purposes, Title 3 companies, issuers are going to be like everyone else. Yeah, you can talk to people about it. You can’t take their money. But that’s an important change for sure. The demo days. Meaning when you’re local science center has a demo day you are now actually allowed to … to attend. It was crazy that you couldn’t attend before. We should mention that they’ve taken some things away. Many Title 3 issuers, the security that they were offering, as you know, were called SAFEs – Simple Agreement for Future Equity. Very popular. The S.E.C. has been convinced by someone that that is not an appropriate instrument for a small company to issue. So, they’re going to absolutely get rid of them. Another very popular instrument – revenue sharing notes. It isn’t clear from the proposals, but it sure looks like they’re getting rid of revenue sharing notes or at least want to.

Eve: [00:17:04] Interesting.

Mark: [00:17:05] You know what the lord giveth, the lord taketh away. I know there’s going to be, during the public comment period, there’s going to be a lot of people complaining about those two things. We did take a couple steps backward, but I think we took about 10 steps forward, so, on the whole, they have made the market much more robust. Yeah, I think it’s very exciting, I, you know this is a world that, you know, you and I have both drank the Kool-Aid a long time ago. This is about providing capital for lots of people whose access to capital has hitherto been restricted. And it’s also about providing investment opportunities to ordinary Americans that have hitherto been reserved for the ultra-wealthy.

Eve: [00:17:55] Yeah.

Mark: [00:17:55] And that’s why my blog post said, you know, this is not about Wall Street. It is actually about undermining Wall Street. It is about a sort of direct to the people, democratic American capitalism. And I think this is a really good step in the right direction. I don’t see any down side personally.

Eve: [00:18:17] Yeah, so you think the number of funding portals is going to explode?

Mark: [00:18:20] I do.

Eve: [00:18:21] It’s about 50 now, right?

Mark: [00:18:23] Something like that, yeah.

Eve: [00:18:24] And in real estate?

Mark: [00:18:26] I do. I think you’re going to have some competitors, which is good. Yeah, I think there are going to be real estate funding portals, I even think, Eve, I think that the big real estate, the Rule 506(c) sites, I think they’re going to consider very seriously having subsidiaries that are funding portals.

Eve: [00:18:47] Interesting.

Mark: [00:18:48] I think it’s a natural to expand their customer base. You know, I’ve always said that portals are like retail stores. And I read a blog post once, saying a portal is like DSW. And DSW doesn’t limit the kinds of shoes that it sells, and it wants every kind of customer to walk in the door, right? And even, you know, a brand like Mercedes Benz, they don’t sell only a 100,000 dollar cars, you know, they sell a 35,000 dollars car. Why? Why do they do that? It’s not to make money from selling a 35,000 dollar car. It’s to get people into the showroom.

Eve: [00:19:33] Yes.

Mark: [00:19:33] And expand their demographic customer base. And I think that’s the natural route for portals as well. We want to accredited investors. We want non-accredited investors. We want everyone, right? I mean, that’s always make sense to me.

Eve: [00:19:46] Right. Right right, right. So, can you think of some examples of projects that you saw in the past that if they went live now, would do so much better? Or is that too hard a question?

Mark: [00:19:57] You’re, I mean, you’re the one who would know that.

Eve: [00:19:58] We have an offering live right now, which was just so complicated to put together, a side-by-side offering. And, you know, an opportunity zone fund offering. They really needed a single-purpose entity for the opportunity zone fund investors. And, of course, we couldn’t use it for Reg CF, so the Reg CF investors missed out on the opportunity zone, tax discounts. And, you know, thinking about how that would be put together under the new rules, it would be so easy.

Mark: [00:20:31] Yeah.

Eve: [00:20:31] I spent months putting it together.

Mark: [00:20:35] I mean, probably every project you’ve ever had on your platform.

Eve: [00:20:38] Yes.

Mark: [00:20:39] You would’ve had the ability to pitch it to accredited investors. Simultaneously. And you would have been legally been earning commissions on all of those transactions.

Eve: [00:20:50] Yes. Yeah. That’s a really big problem.

Mark: [00:20:53] I mean, your life would have been very different.

Eve: [00:20:54] Well, I can’t go back five years, can I?

Mark: [00:20:57] No.

Eve: [00:20:58] So, what about the whole ‘not being able to talk about the terms of the deal’? Like that’s been another really huge stumbling block when you do advertise Reg CF offering, you’re not permitted to talk about the teems. You can’t say, you know, the offering is nine percent preferred return. You’re not permitted to say that. You’re not even permitted to say the minimum investment amount. Whereas with a 506(c) offering, you can say all of that. Is that going to change?

Mark: [00:21:27] Not yet. It wouldn’t surprise me if it changed in the future. So, yeah, you’re gonna be stuck with those same advertising limitations. Now, I will just say that you can say those things.

Eve: [00:21:41] Yes, but that’s all you can say, right?

Mark: [00:21:42] But that’s all you can say.

Eve: [00:21:44] Yeah.

Mark: [00:21:45] And you can say a lot. You know, you can say come invest in this fabulous multi-family project in Downtown Pittsburgh, and it’s 72-percent leased and it’s gorgeous and it’s environmentally friendly. You can go on and on and on and say all those things.

Eve: [00:22:04] You can’t say “it’s gorgeous” because it’s in adjective, right?

Mark: [00:22:07] Ok, well, now I think, I can, I think you can say “gorgeous.”

Eve: [00:22:11] No, I can’t.

Mark: [00:22:13] The only thing you can’t say is …

Eve: [00:22:15] I got my knuckles rapped for saying “bold.” Yeah.

Mark: [00:22:20] You just can’t say, and by the way, we’re raising two million dollars for that project. You know? You can talk about the project until you’re blue in the face.

Eve: [00:22:29] Yeah. Well, that’s been pretty good for us because we want to talk about the projects, but still it is a stumbling block. I think people sit up and pay attention when you say you can invest as little as 1,000 dollars and they’re looking at an ad talking about a great project, but they don’t really know. It’s a question of will they click through? Right? It’s definitely a stumbling block.

Mark: [00:22:50] Yes. And it will continue to be.

Eve: [00:22:53] Yes. Ok. So, I want to just shift gears a little bit. We’re doing this a bit backwards. But how did you become an S.E.C. crowdfunding expert, and why?

Mark: [00:23:04] Actually, Eve, I think our stories are in some ways, similar. So, I mean, I’ve always been a boring corporate lawyer. And in being a boring corporate lawyer, I’ve represented entrepreneurs my whole career. And when you represent entrepreneurs, one of the things you spend a lot of time doing is helping them raise capital. Entrepreneurs are always looking for capital, and raising capital used to be, you know, really, really hard. It’s still really hard, but it used to be, before the crowdfunding rules, a lot harder, as as you know. And when I saw the Jobs Act on the horizon, this must happen back in like 2011, which is amazing, of course, how quickly time flies.

Eve: [00:23:50] Yes.

Mark: [00:23:51] But I said, wow, you mean you’re going to be able to use the Internet to raise money? This is huge. It’s transformative. It’s disruptive. It’s fantastic. And I drank the Kool-Aid right away and thought this would just be a great thing for the American economy. And I said, it’s going to be fun and I want to be involved with it. So, I immediately decided that that’s what I was going to do. So, I learned all about it and started writing this blog and started speaking about it in public. And I’m so enthusiastic about it, and the rest is history. So, that’s my story, which in some ways is probably similar to yours, right?

Eve: [00:24:33] Yes.

Mark: [00:24:34] You saw it and you said, aha!

Eve: [00:24:36] Yes. But not enough of us yet. Right. Still a pretty small industry.

Mark: [00:24:41] Still a pretty small industry, but it is growing, you know. People are raising, we talked about five million being a pretty good real estate deal, you know, people are raising 15 million now. And that, when, you know, when you and I got into this industry, the concept of being able to raise 15 million dollars for a deal online was unthinkable.

Eve: [00:25:06] Yes.

Mark: [00:25:06] You know, people were raising 250,000 dollars to do a fix and flip. The industry is now funding from very significant deals. And because entrepreneurs are always looking for capital, you know, the entrepreneurs of the world are really paying attention.

Eve: [00:25:26] Yes. Yeah.

Mark: [00:25:27] I’m a pretty good barometer because I am pretty well-known in the industry and I will, so when I say my phone has sort of been ringing off the hook, that’s a pretty good industry barometer.

Eve: [00:25:40] It is. Yeah.

Mark: [00:25:41] You know, it probably means lots of peoples’ phones have been ringing off the hook. And this latest change really has gotten people’s attention.

Eve: [00:25:49] Yes. Well, it should.

Mark: [00:25:52] So, I think in 2020, I really think the industry, those of us who survive the coronavirus, anyway …

Eve: [00:26:01] Oh, that’s depressing.

Mark: [00:26:02] Yeh, and I … then are going to, you know, really see a significant uptick.

Eve: [00:26:10] Yes. So, I have to ask the next round of improvements that the S.E.C. makes, what do you want to see on that list?

Mark: [00:26:17] So, I get asked that question a lot and I never have a ready answer because I’ve been doing this, you know, I’ve been practicing law for so long. I have learned not to think about possible legislative or regulatory changes because they are so rare and so unpredictable, you know. There are two things you never want to see being made. One is sausage and the other is law. I just focus on the world that I have, that I’m in, rather than on how it might be improved.

Eve: [00:26:57] I get it. The thing I think about is of regulatory burden, which is enormous for small companies. Really enormous.

Mark: [00:27:05] And how would you address that?

Eve: [00:27:08] For a small company that’s never done something like this before. As a member of FINRA, not only are you following, you know, the regulation crowdfunding rules, but you’re also following FINRA’s rules, which require many, many, many things, like WURM compliance of emails and evidencing and things I never knew existed. It’s very time consuming to learn at all, and it’s time consuming to keep it up and to do it properly. And I have a feeling that many platforms are not doing it properly because it’s just too hard. So, I think that really needs to be addressed in one way or another. You know, I don’t know what a full-blown broker/dealer compliance book looks like. I’m sure it’s worse. But in some ways I feel like FINRA wasn’t ready to handle these smaller companies, they’ve never done anything like it before. The compliance is … huge. And, you know, we’re surveilled every quarter, and they said, well, every word. And that that’s their job. So they have to, I’m not saying they shouldn’t, but it’s all required, and it’s a lot.

Mark: [00:28:19] Yeah. And I mean, maybe I would say the next significant change maybe should be from FINRA rather than from the S.E.C..

Eve: [00:28:31] Yes, possibly.

Mark: [00:28:32] I completely agree with you that FINRA didn’t know how to deal with this and they started off with a light touch, you know. The first funding portals that I represented that, they were easy to get approved. And then FINRA just didn’t know what to do. And, you know, the easy answer is from a regulatory point of view was always to make it more difficult. And so we’ve ended up in this kind of crazy situation where funding portals, small, small organizations, are subject to the same regulatory treatment as, you know, as Morgan Stanley. And it it is clearly not a good fit.

Eve: [00:29:16] That’s right. Although I have to say that they’re trying, and in their communications with Small Change, at least, the tone is more about helping us be aware of what we’re supposed to do. So, it’s not a bad tone, but still, the regulatory burden is there. In a sense, I think FINRA got lumped with this without anyone much thinking about the consequences. Does that make sense?

Mark: [00:29:39] Yes. I mean, I’m not attacking FINRA, because, as you say, they’re just doing their job. No one told them, you know, you should act differently with the respect that this particular species of FINRA member, as you know, I mean, these days we’re submitting policies and procedures to FINRA that are, you know, 75 pages long …

Eve: [00:30:03] Oh, wow.

Mark: [00:30:03] … could be a two person company where, you know.

Eve: [00:30:07] Yeah.

Mark: [00:30:07] The policies and procedures amount to the two people saying this is how we’re going to regulate ourselves. You know, there’s no one else to regulate. There’s no one to supervise.

Eve: [00:30:17] Yeah, no, no. I know. It’s a shame.

Mark: [00:30:21] It’s almost been an absurdity, but there you go.

Eve: [00:30:25] So, yeah. Let’s root for FINRA making the next change or, something happening that permits for FINRA to make the next change, because I’m not sure they’re fully in control of that themselves. I don’t really, I don’t really know. But, you know, we we pay a lot of money to a company called Smarsh to archive all our emails, all our websites, everything, so that they’re all WURM compliant. That’s a big burden for a tiny company.

Mark: [00:30:52] Well, there you go.

Eve: [00:30:52] We also pay a lot for insurance, which is crazy expensive. I have a feeling that many funding portals don’t …

Mark: [00:31:00] Just don’t do it. Yeah.

Eve: [00:31:01]  … pay for insurance, because they can’t afford it. I like to sleep at night.

Mark: [00:31:05] I guess, what from the FCC, you know, rule 204, which is that burdensome advertising rule that you were alluding to earlier. That does seem a little too harsh. The idea of it, the theory of regulation crowdfunding is that every investor should have access to exactly the same information at all time.

Eve: [00:31:29] That’s right. Yep.

Mark: [00:31:31] And so that’s why they don’t let you freely advertise. They want all attention to get focused back to the funding portal.

Eve: [00:31:39] Right.

Mark: [00:31:40] Which is supposed to be the sole source of the information. And so, yeah, I totally understand that. I’m not going to say there’s no reason for the rule. I think maybe this is an example of ideology, sort of, getting the better of practicality. The rule is just impractical. And …

Eve: [00:32:02] Yes. Yeah.

Mark: [00:32:04] The ideological purity of it I think is outweighed by the burden that it places on, again, on very, very small companies.

Eve: [00:32:13] We’ve ended this on a bad note.

Mark: [00:32:15] Yeah, but well we’re sort of searching for ways that maybe in five years from now, maybe the S.E.C. will make the rules even better.

Eve: [00:32:26] Yeah.

Mark: [00:32:26] But these little rules, you know, again, we’re dealing with tiny companies and you know, big companies have the resources to hire lawyers, like me, or even have their own in-house lawyers. But these are tiny companies. So, a lot of these rules, as you know, in your position as a funding portal end up just being tripping points, you know, traps for the unwary.

Eve: [00:32:50] Yes.

Mark: [00:32:51] Yes, we could do with fewer of them. But on a positive note, again, 2020 is going to be a very, very good year.

Eve: [00:33:00] Yes, it is. And final question, what’s next for you?

Mark: [00:33:06] What’s next for me is, you know, I’ve just started a new law firm, Lex Nova Law. Super exciting, fun, high tech, really cool, hiring more people, training more people to learn about these rules. And part of my job in the crowdfunding industry is to educate people. So, I love being on the forefront of education. And another part of my job, I think, is to make the industry better. And that means more compliant, but also more efficient. The Internet, which is what crowdfunding is all about, it requires efficiency, right? It is …

Eve: [00:33:54] Yes.

Mark: [00:33:55] It is a tough taskmaster. You know, Amazon. You try to compete with Amazon in retail, man, you find out how efficient they are. So, lawyers, the key kind of friction points in the syndication world, in the capital formation world. You know, lawyers have to become more efficient. And I work on that all the time and try to work with industry leaders to make the crowdfunding industry better for investors, in part by making it more efficient. So, that’s the answer your question

Eve: [00:33:55] Great. Well, I’ve had the privilege of working with you on that. And I agree. Efficiency really matters. Thank you so much for joining me. And I also can’t wait to see what the year holds.

Mark: [00:34:42] Thank you so much.

Eve: [00:34:44] Okay.

Mark: [00:34:44] Have a great day out in sunny Pittsburgh.

Eve: [00:34:51] That was Mark Roderick. We got into the weeds together about the proposed improvements to regulation crowdfunding. He and I both understand what these changes will mean to capital formation. As Mark said, these proposals are great for the crowdfunding industry and for American capitalism. They’re not about Wall Street. They’re about small companies and ordinary American investors, where jobs and ideas come from. You can find out more about impact real estate investing and access to the show notes for today’s episode at my website, EvePicker.com. While you’re there, sign up for my newsletter to find out more about how to make money in real estate while building better cities. Thank you so much for spending your time with me today. And thank you, Mark, for sharing your thoughts with me. We’ll talk again soon. But for now, this is Eve Picker signing off to go make some change.

Image courtesy of Mark Roderick

Why choose?

March 23, 2020

It’s becoming increasingly important for investors of all levels to make socially conscious investments ensuring that their investments align with their values. Broadly referred to as impact investing, this type of investing means supporting organizations, businesses and projects that will have a positive social or environmental impact.

While impact investing has historically been associated with high net-worth individuals, in recent years it’s gained increased popularity with middle-class investors who, though having more limited resources or capital, nevertheless wish to have their investments return more than just mere financial dividends. But, understandably, some people may find themselves torn between investing in something that will have a positive impact and investing solely based on return.

The encouraging reality is that investors don’t have to make that choice – you can make impact investments and still see market or above-market returns, and there are an increasing number of examples of ways to do this. Janine Firpo is an interesting case study of an investor that’s gone all-in on impact investing and is consistently realizing strong returns on those investments.

A case study

Janine had been working in the computer and multimedia industry since the 80s, and in 1995 she took a year off to travel. During that year, she backpacked through sub-Saharan Africa and was powerfully moved by the poverty that she saw in the region. Returning from that year abroad she had become determined to find ways to use her technology and business knowledge to help reduce poverty.

As a result, she spent more than two decades traveling the globe, helping to bring technologies and development projects to Africa, Southeast Asia and other regions with high rates of poverty in her role with several philanthropies. After this period of nearly constant travel, she retired from that career and returned to the Bay Area, where she became familiar with the broader ideas of social philanthropy and impact investing. She began to realize that she had committed herself to leading a life of value but hadn’t carried that same philosophy over to her investments.

A vision for investing

Janine felt that her investments were, in a way, working against efforts in her own life and work. With this realization, she made the decision to invest everything she had in a way that supported her values, and that might help to build the world she wanted. She shared this vision with her financial advisors but found that they were not able to fully meet her goals. So, she took back control of the assets and began to invest them herself.

Janine has since spent extensive amounts of time researching investment opportunities and finding investments that align with her thinking, and not surprisingly she has found that it can be a time-consuming and remarkably difficult project to start from scratch. In order to help make impact investing easier for others, she is currently writing a book that condenses and shares the results of her efforts, while providing step-by-step guidance for value-aligned investing.

Returns for impacting investing

When asked whether she is getting acceptable returns from these new investments, Janine responded with an emphatic, “Yes!”, noting that “this is not about giving up returns. This has never been about giving up returns.” As an example, she shared her experience with a particular holding in her portfolio. She used the website AsYouSow.org to learn more about how this holding aligned with the values she prioritized and found out that it had a rating of D (not good). She then found another holding with A and B ratings on those values and invested in that instead and found that over a 10-15-year time frame, the alternative investment actually had yielded higher returns. Clearly, a win-win for Janine, and would also be for many middle-class investors looking to protect and grow their savings and retirement funds.

To learn more about Janine Firpo’s efforts to make impact investing more accessible, listen to her full podcast interview. Or check out some of the real estate impact investment opportunities available at Small Change.

Image from Piqsels licensed CC0, Public Domain

« Previous Page
Next Page »

Primary Sidebar

sign up here

APPLY TO BE A PODCAST GUEST

More to See

The Seven

August 29, 2025

Real estate and women.

February 26, 2025

Oculis Domes.

February 25, 2025

FOLLOW

  • LinkedIn
  • RSS

Tag Cloud

Affordable housing Climate Community Creative economy Crowdfunding Design Development Environment Equity Finance FinTech Gentrification Impact Investing Mobility Offering Opportunity zones PropTech Technology Visionary Zoning

Footer

©rethinkrealestateforgood.co. The information contained on this website is for general information purposes only. Nothing on this website is intended as investment, legal, tax or accounting strategy or advice, or constitutes an offer to sell, solicit or buy securities.
 
Any projections discussed or made may not be accurate and do not guarantee a specific outcome. All projections or investments are subject to risk due to uncertainty and change, including the risk of loss, and past performance is not indicative of future results. You should make independent decisions and seek independent advice regarding investments or strategies mentioned on this website.

Recent

  • Vacant Upper Floors: Unlocking Downtown Housing
  • Podcast hiatus.
  • Pop City: Changing the Conversation
  • The Mulberry
  • Mount Vernon Plaza

Search

Categories

Climate Community Crowdfunding Development Equity Fintech Investing Mobility Proptech Visionary


Copyright © 2026 · Magazine Pro on Genesis Framework · WordPress · Log in